Fannie Mae, Freddie Mac & the FHA's New Reconsideration of Value Requirements: What Lenders Need to Know
New Requirements Overview
Fannie Mae, Freddie Mac, and the FHA have introduced new standardized requirements for the Reconsideration of Value (ROV) process. These changes aim to create a more transparent and equitable process for borrowers who believe their appraisal is inaccurate.
What Is a Reconsideration of Value?
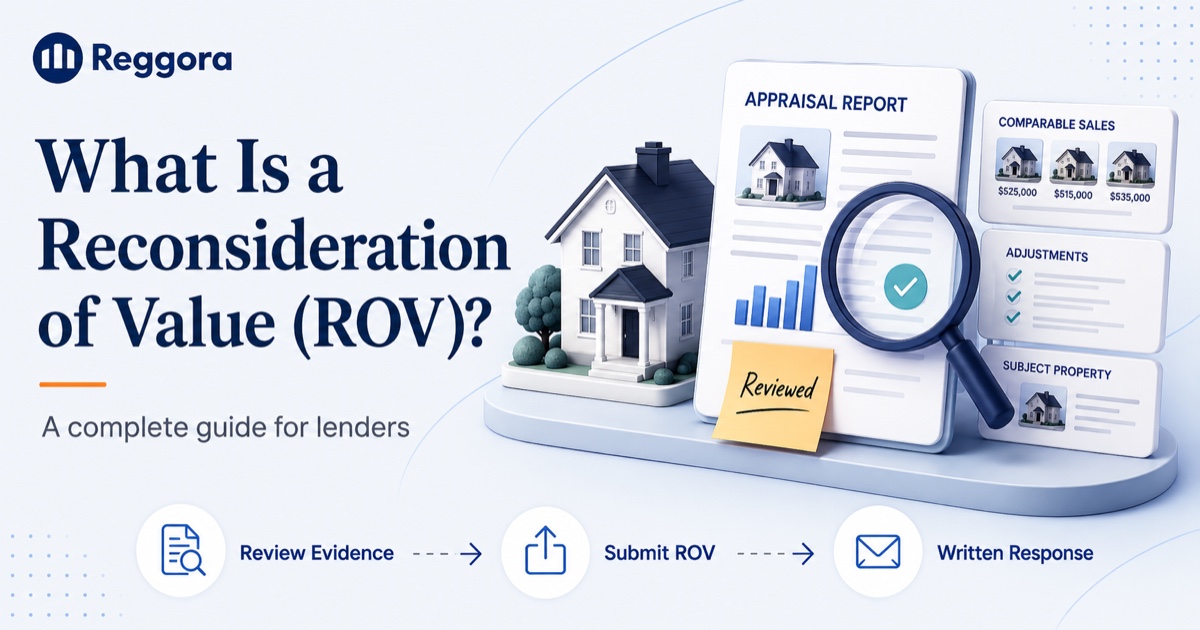
A Reconsideration of Value (ROV) is a formal request to an appraiser to reconsider their value opinion, typically when a borrower or lender believes the appraisal does not accurately reflect the property's market value. The new requirements standardize how these requests must be handled.
Key Changes for Lenders
1. Standardized ROV Process
Lenders must now follow a defined process for handling ROV requests:
- Accept ROV requests from borrowers at any point before closing
- Forward all ROV requests to the appraiser with supporting documentation
- Require appraisers to respond within a specified timeframe
- Document the entire ROV process in the loan file
2. Borrower Rights
Borrowers now have explicit rights in the ROV process:
- The right to submit a ROV request with supporting data
- The right to receive a written response from the appraiser
- The right to submit additional comparable sales or property information
3. Anti-Discrimination Provisions
The new requirements include strengthened provisions to address potential appraisal bias, including requirements for lenders to review ROV requests for potential fair lending concerns.
How Reggora Helps
Reggora's platform streamlines the ROV process with:
- Automated ROV workflows: route requests to appraisers with proper documentation
- Compliance tracking: ensure all requirements are met and documented
- Timeline management: automated reminders for response deadlines
- Audit trail: complete documentation for regulatory compliance
Need help with ROV compliance? Request a demo to see how Reggora can streamline your ROV process.